
 NZ
 IND
 NAM
 IRE
 MOZ
 UGA
 Aston Villa
 Man City
 Rayo
 Elche
 GMB
 ZMB
 NGA
 LES
 Cagliari
 Bologna
 IPS1
 NFO1
 ALA1
 MCF1
 TOR3
 MON2
 BRE1
 NICE2
 TAS129/7 (23.3/35 ov, target 276)
 VIC304/7 (50 ov)
 WA
 NSW38/1 (9/50 ov)
 NZ-A135/3 (41 ov)
 IND-A113
 DHA
 RAJ
 MYMS
 CHATT
 RAN
 BAR
 SYL
 KHU
 MEX-W
 ARG-W
 UAE
 NED
 AFG170/3 (34.3/50 ov, target 170)
 ZIM169
 IND-W200/1 (27.1/50 ov, target 198)
 ZIM-W197
 DOLPH56/0 (3.5/8 ov, target 56)
 SWD51/4 (8/8 ov)
 WSW1
 BRI1
 Como
 Sassuolo
 Augsburg
 Union Berlin
 Cologne
 Schalke
 Mainz
 Bremen
 RB Leipzig
 Elversberg
 VFB2
 BMG3
 AHL4
 KHA1

Mistral AI’s stated goal is to build 1 gigawatt of European compute by 2030—a scale ambition that matters because AI buyers increasingly pay for capacity, not just model access. If that capacity is timed right, it could turn Mistral into a long-term infrastructure vendor; if it’s late, customers will lock elsewhere and the “compute lead” becomes a brand risk.
Here’s the thing: demand for AI compute is outpacing traditional procurement cycles, and enterprises don’t want another round of “best-effort” capacity when latency, compliance, and service continuity are on the line. Mistral AI announced this strategic plan, and VentureBeat covered it on August 11, 2026, while also framing the company’s push to secure enterprise customers early. The details are based on leaks and supply-chain reports, not yet officially confirmed, but the direction is clear—Mistral wants to control supply and use contracts to finance the build.
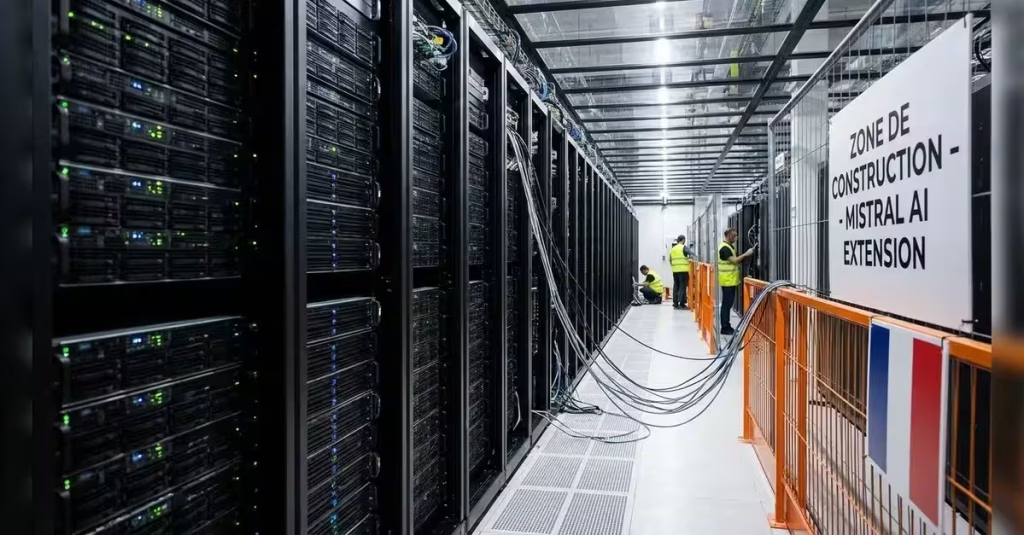
Mistral AI compute: 1) The bottleneck isn’t models—it’s capacity continuity (and Mistral knows it)
The problem: AI workloads are increasingly constrained by where compute can be deployed, how fast capacity can be scaled, and how reliably it can be delivered under enterprise terms. Even when a model is strong, the business outcome depends on throughput consistency for training runs, retrieval pipelines, and production inference.
Worth noting: capacity is also where governance lives—data locality, vendor controls, and predictable SLAs. That’s why Mistral AI’s “European compute” framing is so commercially specific: European enterprise procurement tends to demand audit trails and jurisdictional clarity, not just raw performance.
2) The root cause is procurement latency colliding with infrastructure lead times
Here’s the root cause: the time from “we need capacity” to “capacity is usable” is often longer than the time it takes to choose a model. Enterprises want predictable pricing, reserved capacity options, and service continuity; infrastructure providers want advance commitments to finance power, networking, and data centre capacity.
Mistral AI’s playbook (as described by VentureBeat) is essentially to shorten the gap between these timelines by chasing enterprise customers now, before the capacity is fully online. That’s why the company’s announced plan to reach 1 gigawatt by 2030 isn’t just engineering—it’s a go-to-market strategy built around long-term deals.
That said, critics will point out a harsh trade-off: committing to infrastructure scale can divert focus from model iteration speed. If execution slips, customers may view it as “infrastructure theatre” rather than a reliable service roadmap.
3) Candidate solutions: reserve compute, partner for capacity, or build later (trade-offs included)
The compute question boils down to three realistic paths enterprises and model providers can choose. Each option has a downside, and that downside decides whether customers stay or churn.
| Option | What it does best | Downside / risk |
|---|---|---|
| Lock reserved capacity via long-term contracts | Stabilizes cost and SLAs | If supply arrives late, buyers get stuck with sunk commitments |
| Partner with existing European data-center operators | Faster time-to-market | Less control over pricing, locality, and roadmap alignment |
| Wait to build until demand is proven | Avoids early capex risk | Capacity crunch returns, and customers sign with competitors first |
Mistral AI Compute: Here’s the thing: Mistral’s announced approach appears to combine the first two—sign customers early to finance compute, while building within Europe to reduce procurement friction. According to VentureBeat, the intent is also to lock in long-term contracts for the compute power that’s coming.
Worth noting: partnership-only strategies can be “quick win” but often collapse under renegotiation pressure when demand spikes. Waiting-only strategies can preserve optionality, but they usually lose mindshare during the period when enterprises are actively selecting vendors. So what should enterprises do?
If they want governance, predictable delivery, and European deployment, they should pressure-test the contract terms (timelines, penalties, and fallback capacity) rather than judge the plan only by headline capacity targets. If Mistral AI’s build milestones are enforceable, the gigawatt framing can translate into real procurement confidence. Stay tuned for more on Mistral AI.
4) Our recommendation: if you’re choosing vendors, prioritize enforceable compute roadmaps
We recommend treating this like a capacity procurement decision, not a model-choice decision. Mistral AI’s gigawatt-by-2030 ambition and early enterprise targeting—covered by VentureBeat—suggest a vendor strategy that could reward buyers who want long-run supply certainty in Europe.
But here’s the tension: buyers should avoid assuming scale promises automatically become capacity reality. The counterargument is straightforward—execution risk is real whenever infrastructure and AI roadmaps are coupled.
Our outlook: if Mistral can convert “compute intent” into contractual, milestone-backed delivery—backed by transparent governance and clear operational SLAs—then its strategy can become a differentiator. If not, enterprises should diversify across partners and plan for multi-vendor capacity.
Closing takeaway: Choose the vendor whose compute roadmap is contractually enforceable—Mistral’s gigawatt plan only matters if delivery timelines survive procurement scrutiny.
Related Articles
FAQs: Mistral AI
What does “1 gigawatt of European compute by 2030” actually mean?
It’s an infrastructure capacity target aimed at making AI compute available at very large scale across Europe. The public framing (including VentureBeat’s coverage) focuses on building that capacity and securing enterprise commitments ahead of full availability, but specific technical and commercial details aren’t confirmed in the reporting we have.
Why does “locking in customers now” matter for AI compute plans?
Enterprises don’t just buy models; they buy continuity—capacity reservations, predictable latency, compliance alignment, and SLAs. Early contracts help finance multi-year infrastructure work, reducing the risk that the supplier builds first and customers arrive later.
What downside should buyers watch in a gigawatt-scale build?
The biggest downside is schedule and delivery uncertainty. If capacity comes later than promised, customers may face penalties, migration costs, or reduced bargaining power when the market is already constrained.
Was this article helpful?
Your feedback directly improves future articles on this site.




