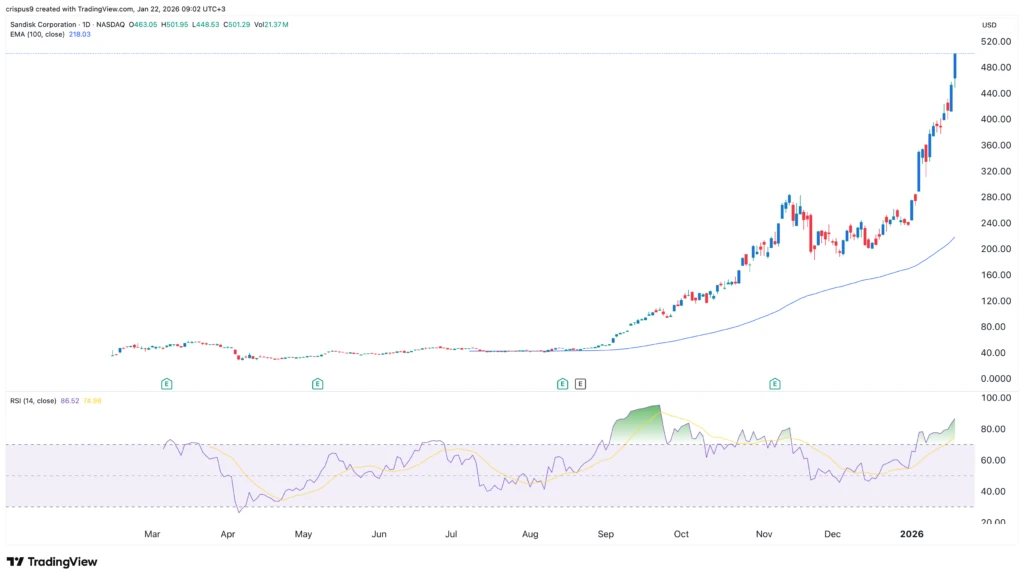
SanDisk (SNDK) stock has exploded in 2026, soaring over 100% as the AI boom drives unprecedented demand for memory chips and storage solutions. The flash storage memory company recently crushed Wall Street’s fiscal second-quarter estimates, reporting earnings of $6.20 per share versus the expected $3.62, with revenue totaling $3.03 billion against a forecast of $2.69 billion.
Table of Contents
AI Infrastructure Fuels Memory Chip Shortage
The AI capex boom has funneled down to SanDisk as hyperscalers build AI systems requiring large volumes of memory chips to store and move data for AI models. At CES 2026, Nvidia CEO Jensen Huang described memory and storage as the “largest unserved market” in AI, arguing that GPUs are useless without massive, high-speed data storage.
| Performance Metric | Results |
|---|---|
| 2026 YTD Gain | Over 100% |
| Q2 EPS | $6.20 (vs $3.62 expected) |
| Q2 Revenue | $3.03B (vs $2.69B expected) |
| Q3 Revenue Guidance | $4.4B-$4.8B (vs $2.93B expected) |
Blockbuster Earnings Drive Analyst Upgrades
SanDisk’s third-quarter forecast blew away expectations, guiding for between $4.4 billion and $4.8 billion in revenue versus the $2.93 billion expected, with adjusted earnings between $12 and $14 per share—more than double the $5.11 analyst estimate. Raymond James upgraded the stock to outperform rating, citing SanDisk’s pricing momentum as new supply struggles to come online.
Bank of America analyst Wamsi Mohan hiked his price target to a Wall Street-high of $390, noting that Nvidia’s comments about dedicated storage tiers elevate NAND to a more prominent role in AI workloads. Cantor Fitzgerald analyst Christopher Muse believes SanDisk stock could stretch to $800 by the end of 2026, citing NAND flash prices potentially climbing another 50% in fiscal Q3.
Supply Constraints and Pricing Power
Analysts note that demand is exceptionally strong and likely growing, while supply is tightening to the point of potentially being sold out for years, supporting continued strong pricing. SanDisk expects third-quarter gross margins between 65% and 67%, far ahead of the 49.3% expected by analysts.
SanDisk’s BiCS8 technology enhances its competitiveness in the data center market, with momentum in its storage-optimized SSD platform undergoing qualification with hyperscalers. CEO David Goeckeler stated that customers “value supply over price” in the current tight market environment.

Massive Earnings Growth Projections
Analysts estimate SanDisk will report fiscal 2026 earnings of $13.77, up sharply from $2.99 the prior year, with fiscal 2027 earnings pegged at $25.85. Although the stock has rallied, it still trades at a forward price-to-earnings ratio of 28.8, which appears reasonable given the company’s 551.7% estimated EPS jump in fiscal 2026.
From a 52-week low near $28 to a peak above $350, SanDisk’s market capitalization has ballooned into the $40-50 billion range. The company’s transformation into a pure-play storage provider following its Western Digital spin-off has positioned it directly at the intersection of AI and storage infrastructure.
For more stock market analysis and tech investment insights, visit TechnoSports.
FAQs
Why is SanDisk stock rising so dramatically in 2026?
AI-driven demand for memory chips, severe supply shortages, blockbuster earnings beating estimates by 70%, and analyst price targets reaching $800.
What are SanDisk’s Q3 2026 earnings projections?
Revenue guidance of $4.4B-$4.8B and earnings of $12-$14 per share, more than double Wall Street expectations.