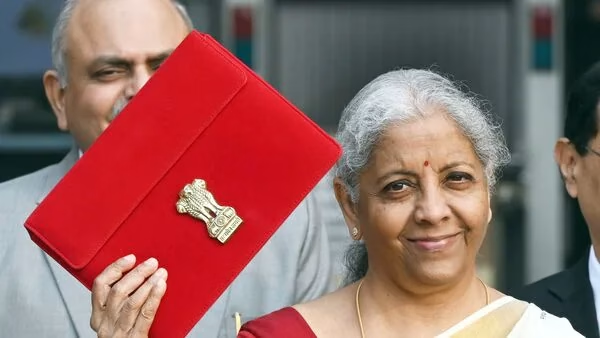
Finance Minister Nirmala Sitharaman’s Budget 2026-27 delivered a thunderbolt to India’s electronics manufacturing ecosystem—doubling the Electronics Component Manufacturing Scheme (ECMS) outlay to ₹40,000 crore and simultaneously launching India Semiconductor Mission 2.0. Together, these two announcements represent the single most aggressive push toward electronics manufacturing self-reliance in Indian history.
This isn’t incremental policy tweaking. It’s a fundamental restructuring of India’s industrial strategy—one that could determine whether the country becomes a genuine global technology manufacturing powerhouse or remains perpetually dependent on imports for critical components.
Table of Contents
The ₹40,000 Crore ECMS Boost: From Assembly to Manufacturing
What Changed and Why
The Electronics Component Manufacturing Scheme launched just nine months ago in April 2025 with an outlay of ₹22,919 crore—already ambitious by Indian policy standards. Within that brief window, the scheme attracted 46 applications committing ₹54,567 crore in total investments across 11 states, creating an expected 51,000 jobs.
The demand clearly exceeded supply. Investment commitments arrived at roughly double the original scheme outlay—a powerful signal that Indian and global manufacturers saw genuine opportunity in component-level production. Sitharaman’s decision to nearly double the outlay to ₹40,000 crore directly responds to this market signal.
The Critical Distinction: Components vs. Assembly
India’s electronics manufacturing story has two chapters—and understanding the difference is essential for grasping why this budget announcement matters so profoundly.
Chapter 1 (2015-2024): The Assembly Era India successfully attracted smartphone assembly operations from Apple, Samsung, Xiaomi, and others. Mobile phone production surged approximately 30 times—from ₹18,000 crore in FY15 to ₹5.45 trillion in FY25. Beneficiaries included Foxconn, Tata Electronics, Dixon Technologies, Lava International, and Samsung.
But assembly alone captures limited value. When Apple assembles an iPhone in India, the phone’s components—processors, displays, cameras, batteries, PCBs—arrive fully manufactured from Taiwan, South Korea, Japan, and China. India’s role was essentially screwing pieces together and putting them in boxes.
Chapter 2 (2025 onwards): The Component Manufacturing Shift The ECMS represents India’s deliberate pivot from assembly toward genuine manufacturing. The ₹40,000 crore allocation targets the invisible but critical components powering all electronic devices:
| Component Category | Examples | Current India Status |
|---|---|---|
| Display Modules | OLED panels, LCD assemblies | Heavily import-dependent |
| Camera Modules | Lens assemblies, image sensors | Minimal domestic production |
| PCBs (Printed Circuit Boards) | Multi-layer circuit boards | Growing but insufficient scale |
| Passive Components | Capacitors, resistors, connectors | Largely imported |
| Optical Transceivers | Fiber optic communication modules | Near-zero domestic production |
| Power Management ICs | Voltage regulators, charging controllers | Import-dependent |
The 22 proposals approved in the third tranche alone project investments of ₹41,863 crore and production of ₹2,58,152 crore, expected to generate 33,791 direct employment opportunities.
Tarun Pathak’s Insight: “True Local Value Addition”
Tarun Pathak, research director at Counterpoint Research, told Business Today: “This enhanced allocation ensures that funding constraints do not limit component manufacturers, underscoring the government’s seriousness in developing a robust electronics component ecosystem in India. This will help to increase the true local value addition in India.”
This quote captures the fundamental shift. “True local value addition” means India stops being a final assembly destination and starts manufacturing the components themselves—capturing significantly more economic value per device produced domestically.
India Semiconductor Mission 2.0: Beyond Chips, Into Ecosystems
The Ambitious Vision
Sitharaman announced ISM 2.0 with an outlay of ₹40,000 crore, stating: “India’s semiconductor mission 1.0 expanded India’s semiconductor sector capabilities. Building on this, we will launch ISM 2.0 to produce semiconductor equipment and materials, develop full-stack Indian IP, and strengthen supply chains.”
The crucial evolution from ISM 1.0 to 2.0 lies in scope. The first mission focused primarily on establishing fabrication units (fabs)—the actual chip manufacturing facilities. ISM 2.0 expands dramatically to encompass the entire semiconductor value chain:
ISM 1.0 Focus:
- Semiconductor fabrication units
- Assembly, testing, marking, and packaging (ATMP)
- Design Linked Incentives for startups
ISM 2.0 Expanded Scope:
- Semiconductor equipment manufacturing
- Specialty materials and chemicals production
- Full-stack Indian intellectual property development
- Supply chain strengthening and localization
- Industry-led research and training centres
- Compound semiconductor fabrication
- Display fabrication facilities
- Silicon photonics and MEMS sensor capabilities
The Progress So Far: ISM 1.0 Achievements
Before understanding where India is heading, context on where it currently stands proves essential:
| Milestone | Details |
|---|---|
| Total ISM Outlay | ₹76,000 crore |
| Approved Projects | 10 semiconductor projects |
| Cumulative Investment | ₹1.60 lakh crore across 6 states |
| HCL-Foxconn Joint Venture | Display driver chip plant near Jewar, UP—20,000 wafers/month capacity |
| CG Semi OSAT Facility | Sanand, Gujarat—first end-to-end OSAT pilot line, commercial production 2026 |
| Tata Electronics | Assembly and testing unit in Assam |
| L&T Semiconductor | Planning first chip by end 2025, $10 billion fab by 2027 |
| First Indigenous Chip | Expected production by mid-2026 (28-90nm technology) |
India’s first indigenous semiconductor chip was announced ready for production at the Global Investors Summit 2025. The HCL-Foxconn plant is designed for 20,000 wafers per month with a design output capacity of 36 million units per month.
The $110 Billion Semiconductor Market Opportunity
India’s demand for chips is expected to rise to $64 billion by 2026 and reach $110 billion by 2030, growing at an annual rate of about 10%. The government sees chip manufacturing as a critical area for national security and economic strength.
Currently, India imports virtually all semiconductors powering its devices. Every smartphone sold in India, every laptop, every EV, every IoT device—all contain chips manufactured abroad. ISM 2.0 aims to capture a meaningful share of this enormous domestic demand through indigenous production.
The PLI Scheme’s Broader Track Record: Validation of the Approach
Electronics Production Transformation
Under PLI schemes, electronics production surged 146%, from ₹2.13 lakh crore in FY 2020-21 to ₹5.25 lakh crore in FY 2024-25. India has attracted committed investments worth ₹67,690 crore in the electronics sector, generating over 28,884 jobs.
This isn’t theoretical success—it’s demonstrated, measurable transformation. India moved from a net importer to a net exporter of mobile phones within a decade, driven directly by PLI incentives attracting global manufacturers.
Cross-Sector PLI Performance
The broader PLI ecosystem spanning 14 sectors has delivered compelling results:
| Sector | Key Achievement |
|---|---|
| Mobile Phones | Production grew 30x in decade; 33 crore units produced in FY24 |
| Pharmaceuticals | India became 3rd largest global player; exports hit 50% of production |
| Automobiles & Auto Components | Allocation jumped from ₹347 crore to ₹2,819 crore |
| Textiles | Allocation surged from ₹45 crore to ₹1,148 crore |
| Overall PLI | ₹12.50 lakh crore in production and sales; 9.5 lakh jobs created |
Exports under PLI schemes surpassed ₹4 lakh crore, driven by key sectors including electronics, pharmaceuticals, and food processing.

Key Companies and Players: Who Benefits Most
Budget 2026’s electronics manufacturing push creates significant opportunities for specific market participants:
Tier 1: Direct Beneficiaries
Dixon Technologies India’s largest contract electronics manufacturer. Already benefiting from Apple’s iPhone assembly shift. Plans a $3 billion LED-to-OLED display fabrication facility under ISM 2.0. Dixon Technologies is active in design and advanced packaging, planning display fab investment that could receive differentiated subsidies under ISM 2.0.
Foxconn (Hon Hai) Global manufacturing giant with expanding India presence. Joint venture with HCL for display driver chip manufacturing. Critical partner in Apple’s India supply chain diversification strategy.
Tata Electronics Apple supplier with semiconductor assembly and testing facility in Assam. Positioned to capture both smartphone assembly and component manufacturing value chains.
Kaynes Technology and Syrma SGS Mid-cap electronics manufacturers that saw shares jump significantly following the budget announcement—reflecting market recognition of their positioning within the ECMS and PLI beneficiary universe.
Tier 2: Ecosystem Enablers
Semiconductor Equipment Suppliers: Companies providing cleanroom infrastructure, lithography equipment, and testing machinery will see demand surge as ISM 2.0 prioritizes equipment manufacturing.
Specialty Chemical Companies: MSMEs are now eligible for long-term procurement contracts with global players like Micron, Foxconn, and Renesas. Dedicated cluster parks ensure high-purity materials and globally accredited chemicals are sourced locally, resulting in a 15-30% cost reduction compared to global peers.
Training and Skill Development Firms: ISM 2.0’s emphasis on industry-led research and training centres creates significant opportunities for educational institutions and skill-building companies.
Challenges: The Road Ahead Is Not Without Obstacles
Capital Intensity Reality
Each semiconductor fab costs $5-10 billion, and the collapse of the Vedanta-Foxconn JV highlights investor risk. Delays in disbursement, Centre-State coordination issues, and regulatory uncertainty have slowed project execution.
Building genuine semiconductor manufacturing capability requires patient capital, world-class talent, and sustained political commitment spanning multiple election cycles—challenges India has historically struggled to maintain consistently.
Import Dependency Persistence
India remains dependent on imports for lithography, wafers, and specialty gases. Geopolitical risks, such as US-China tensions and supply shocks, further complicate India’s entry-level competitiveness.
ISM 2.0 explicitly addresses this gap by prioritizing equipment and materials manufacturing alongside chip fabrication—a more realistic approach than attempting to build advanced fabs without supporting infrastructure.
Talent Gap
Semiconductor manufacturing requires highly specialized engineers and technicians. India’s education system produces technology graduates in abundance but lacks the semiconductor-specific training pipeline that Taiwan, South Korea, and Japan built over decades. ISM 2.0’s training centre mandate represents a critical first step, but building genuine expertise requires sustained investment over 5-10 years.
Geopolitical Complexity
India is working with countries like the United States, Japan, and members of the European Union to improve its semiconductor capabilities. Under a joint program with the US called iCET, India is gaining access to advanced technologies including those needed for chips used in power electronics.
These international partnerships provide technology access but also create dependencies. India’s semiconductor strategy must balance leveraging foreign partnerships with building indigenous capabilities.
The Strategic Timeline: What to Expect When
| Timeline | Expected Milestone |
|---|---|
| Mid-2026 | First indigenous Indian chip enters commercial production |
| 2026-2027 | CG Semi OSAT facility reaches full commercial capacity |
| 2027 | L&T Semiconductor’s first fab operational |
| 2027-2028 | HCL-Foxconn display driver chip plant reaches full capacity |
| 2028-2030 | Dixon Technologies display fab operational (if approved) |
| 2030 | India targets $110 billion semiconductor market participation |
What This Means for India’s Technology Future
Budget 2026’s electronics manufacturing announcements represent a potential inflection point in India’s industrial trajectory. The combination of ECMS outlay doubling and ISM 2.0 launch creates a comprehensive policy framework addressing the entire electronics value chain—from raw materials and chemicals through components, semiconductors, and finished devices.
Success depends on execution speed, sustained political commitment, and India’s ability to attract and retain world-class talent. The policy framework is now arguably the strongest it has ever been. Whether India converts policy intent into manufacturing reality will determine whether the country achieves genuine technological sovereignty or remains perpetually dependent on foreign supply chains for the components powering its digital economy.
Industry leaders emphasize that India must move beyond finished-device assembly toward a stronger local supply chain for components—from memory and semiconductors to advanced processing hardware. Budget 2026 provides the financial firepower to attempt precisely that transformation. The next three years will reveal whether India’s manufacturing ambitions finally match its industrial policy ambition.
Track India’s electronics manufacturing evolution and semiconductor mission progress at TechnoSports.co.in.